

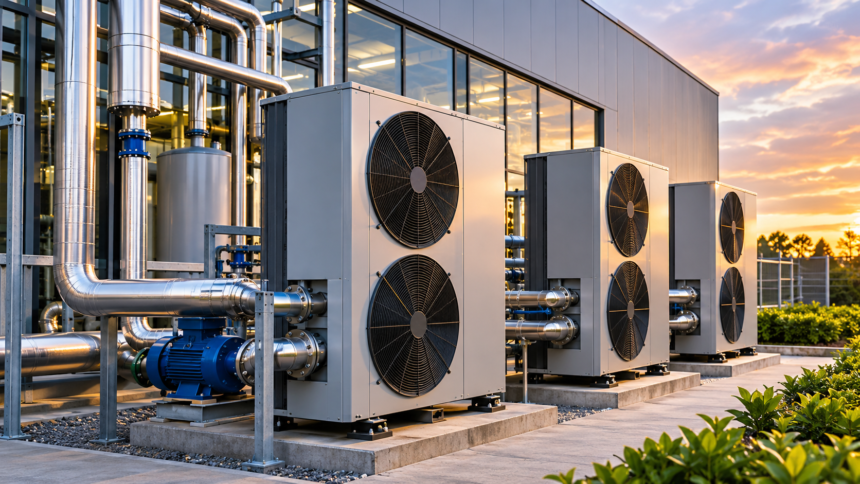
The global heat pump market is gaining momentum as governments, businesses and households accelerate the transition towards electrified heating and cooling. According to research by MarketsandMarkets, the market is projected to grow from USD 88.81 billion in 2026 to USD 169.04 billion by 2031. This represents a compound annual growth rate (CAGR) of 13.7%.
- Electrification and Decarbonisation Drive Market Growth
- Industrial Heating Creates New Opportunities
- Technology Innovation Reshapes the Market
- Air-to-Water Heat Pumps Lead Technology Growth
- Commercial Buildings Emerge as a Fast-Growing Segment
- North America Leads Regional Growth
- Global Manufacturers Strengthen Competition
- What the Market Expansion Means for the Energy Industry
The expansion reflects a broader transformation in global energy consumption. Heating and cooling have traditionally depended heavily on fossil fuels. However, growing decarbonisation commitments, energy security concerns and improvements in equipment efficiency are accelerating the adoption of heat pump technology.
For the industrial sector, this transition presents opportunities beyond conventional building heating. Manufacturers are increasingly exploring heat pumps for process heating, hot water production and district energy applications. These developments are creating new demand for efficient thermal systems, advanced components and integrated energy solutions.
Electrification and Decarbonisation Drive Market Growth
Three major forces are shaping the expansion of the global heat pump market: building electrification, emissions reduction policies and the replacement of conventional fossil-fuel heating equipment.
Governments across major economies are introducing policies and incentives to encourage the adoption of electric heating technologies. These measures support national emissions reduction targets while reducing dependence on natural gas and heating oil.
Energy security is another important consideration. Countries reliant on imported fossil fuels are increasingly looking towards electrification and domestic renewable power generation. Heat pumps offer a pathway to diversify heating energy sources while improving overall energy efficiency.
Adoption is particularly strong in the United States, China, Europe and Japan. China remains the world’s largest heat pump market by volume, supported by its extensive manufacturing capacity and government-led electrification initiatives.
In the United States, heat pump sales have also gained significant ground against conventional gas furnaces. The technology is increasingly becoming a mainstream option for residential heating and cooling rather than a specialised alternative.
Industrial Heating Creates New Opportunities
Although buildings remain the dominant application for heat pumps, industrial applications are emerging as an important growth opportunity.
Manufacturers are exploring heat pump technology to supply process heat, recover waste heat and improve energy efficiency across production facilities. Food processing, chemicals and selected manufacturing operations offer particularly promising applications.
Commercially available heat pump technologies could technically supply approximately 20% of global industrial heat demand. Much of this opportunity lies in low- and medium-temperature processes, where existing technologies can provide suitable operating temperatures.
High-temperature heat pumps are also expanding the technology’s industrial potential. These systems are being developed to serve applications requiring higher process temperatures, potentially reducing the need for conventional fossil-fuel boilers.
District heating represents another emerging application. Heat pumps can extract thermal energy from air, water, wastewater and industrial waste heat. This energy can then support centralised heating networks serving residential, commercial and industrial users.
The growing deployment of these systems will increase demand for efficient compressors, heat exchangers, circulation pumps, control systems and other thermal management components.
For the African market, these developments are particularly relevant to industrial facilities seeking to improve energy efficiency and reduce dependence on conventional heating fuels. Food and beverage processing, agro-industrial operations and manufacturing offer potential areas for future adoption.
Technology Innovation Reshapes the Market
Market growth is accompanied by significant advances in equipment design, refrigerants and system integration.
Air-to-water heat pumps, heat pump water heaters, smart controls and high-temperature systems are among the technologies attracting increasing attention.
Air-to-water systems are particularly important because they transfer heat from outdoor air into water-based heating circuits. They can provide space heating, domestic hot water and, in suitable configurations, cooling.
The technology is increasingly being adopted in residential and commercial buildings, particularly in markets transitioning from conventional boiler-based heating.
Refrigerant innovation is another major development. Manufacturers are moving towards refrigerants with lower global warming potential (GWP), including natural refrigerants such as propane (R290) and carbon dioxide (CO2).
These alternatives can support environmental objectives while creating new engineering requirements. Equipment manufacturers must consider refrigerant properties, operating pressures, safety requirements and system efficiency when designing new products.
Smart controls are also improving heat pump performance. Integration with building management systems, energy monitoring platforms and thermal storage enables operators to optimise energy consumption.
These capabilities can help commercial facilities coordinate heating and cooling demand with electricity tariffs, available renewable power and wider building energy requirements.
Air-to-Water Heat Pumps Lead Technology Growth
Among the different technology categories, air-to-water heat pumps are expected to record the highest CAGR through 2031.
Europe is an important market for these systems, supported by the electrification of space heating and domestic hot water production.
Their ability to replace conventional fossil-fuel boilers makes them attractive for both new construction and building renovation projects. A single system can provide multiple thermal services, depending on its configuration.
The adoption of lower-GWP refrigerants, including R290 and R32, is also influencing product development.
Manufacturers are investing in improved system efficiency, operating temperature ranges and integration with existing heating infrastructure. These developments are expanding the potential applications of air-to-water technology.
Commercial Buildings Emerge as a Fast-Growing Segment
Commercial buildings represent another important growth opportunity.
Hotels, hospitals, offices, shopping centres and industrial facilities require substantial energy for heating, cooling and hot water production.
Heat pumps can provide these services through integrated systems, reducing the need for separate heating and cooling equipment.
Larger installations can also connect with building management systems and thermal energy storage. This allows facility operators to optimise operating schedules and manage electricity consumption more effectively.
The potential to integrate heat pumps with rooftop solar installations and other renewable energy sources further strengthens their appeal.
For commercial property owners, the investment case increasingly combines energy efficiency, operating cost management and emissions reduction.
North America Leads Regional Growth
North America is projected to record the fastest regional growth during the forecast period, supported by replacement demand and increasing electrification of building heating.
The United States is a particularly important market. Heat pumps have gained substantial market share as consumers increasingly adopt systems capable of providing both heating and cooling.
More than one-fifth of US households already use heat pumps for space heating, creating an established market for equipment replacement and upgrades.
The widespread availability of air-conditioning infrastructure also presents an opportunity. Reversible heat pump systems can provide heating and cooling through similar distribution arrangements, potentially reducing the need for extensive building modifications in suitable properties.
Government incentives, domestic manufacturing investment and energy efficiency programmes are further supporting market development.
Canada also presents opportunities as building owners explore alternatives to conventional heating systems, although colder operating conditions require appropriate equipment selection and system design.
Global Manufacturers Strengthen Competition
The competitive landscape comprises established HVAC manufacturers, electronics companies and diversified industrial technology suppliers.
Major participants include Daikin Industries, Carrier, Mitsubishi Electric Corporation, Midea Group, Panasonic Holdings Corporation, Bosch Thermotechnology, LG Electronics, Vaillant Group, Viessmann Climate Solutions, Ariston Group, Trane Technologies, Johnson Controls, Fujitsu, A. O. Smith Corporation and NIBE Industrier.
These companies are competing through product development, manufacturing expansion, acquisitions and geographical diversification.
Investment is particularly focused on improving equipment efficiency, developing low-GWP refrigerant solutions and expanding residential, commercial and industrial product portfolios.
Manufacturers are also strengthening their service networks and technical support capabilities to address the growing requirements of heat pump installations.
As competition intensifies, product reliability, lifecycle operating costs, installation expertise and after-sales support will remain important factors influencing purchasing decisions.
What the Market Expansion Means for the Energy Industry
The projected expansion of the global heat pump market signals a significant shift in how buildings and industries generate and manage thermal energy.
While residential and commercial buildings will remain important demand centres, industrial process heating and district energy applications could broaden the technology’s role in global energy systems.
The transition will also create opportunities across the wider equipment supply chain. Compressors, heat exchangers, circulation pumps, valves, controls and thermal storage technologies will become increasingly important to system performance.
For Africa, the opportunity will depend on local energy costs, electricity reliability, climate conditions, industrial requirements and access to suitable equipment and technical expertise.
As investment in energy efficiency and industrial decarbonisation grows, heat pumps could become an increasingly relevant option for selected commercial and industrial applications.
The next phase of market development will therefore depend not only on equipment innovation but also on supportive policies, financing, skilled installation networks and the integration of electrified heating with reliable energy infrastructure.